Key Takeaways
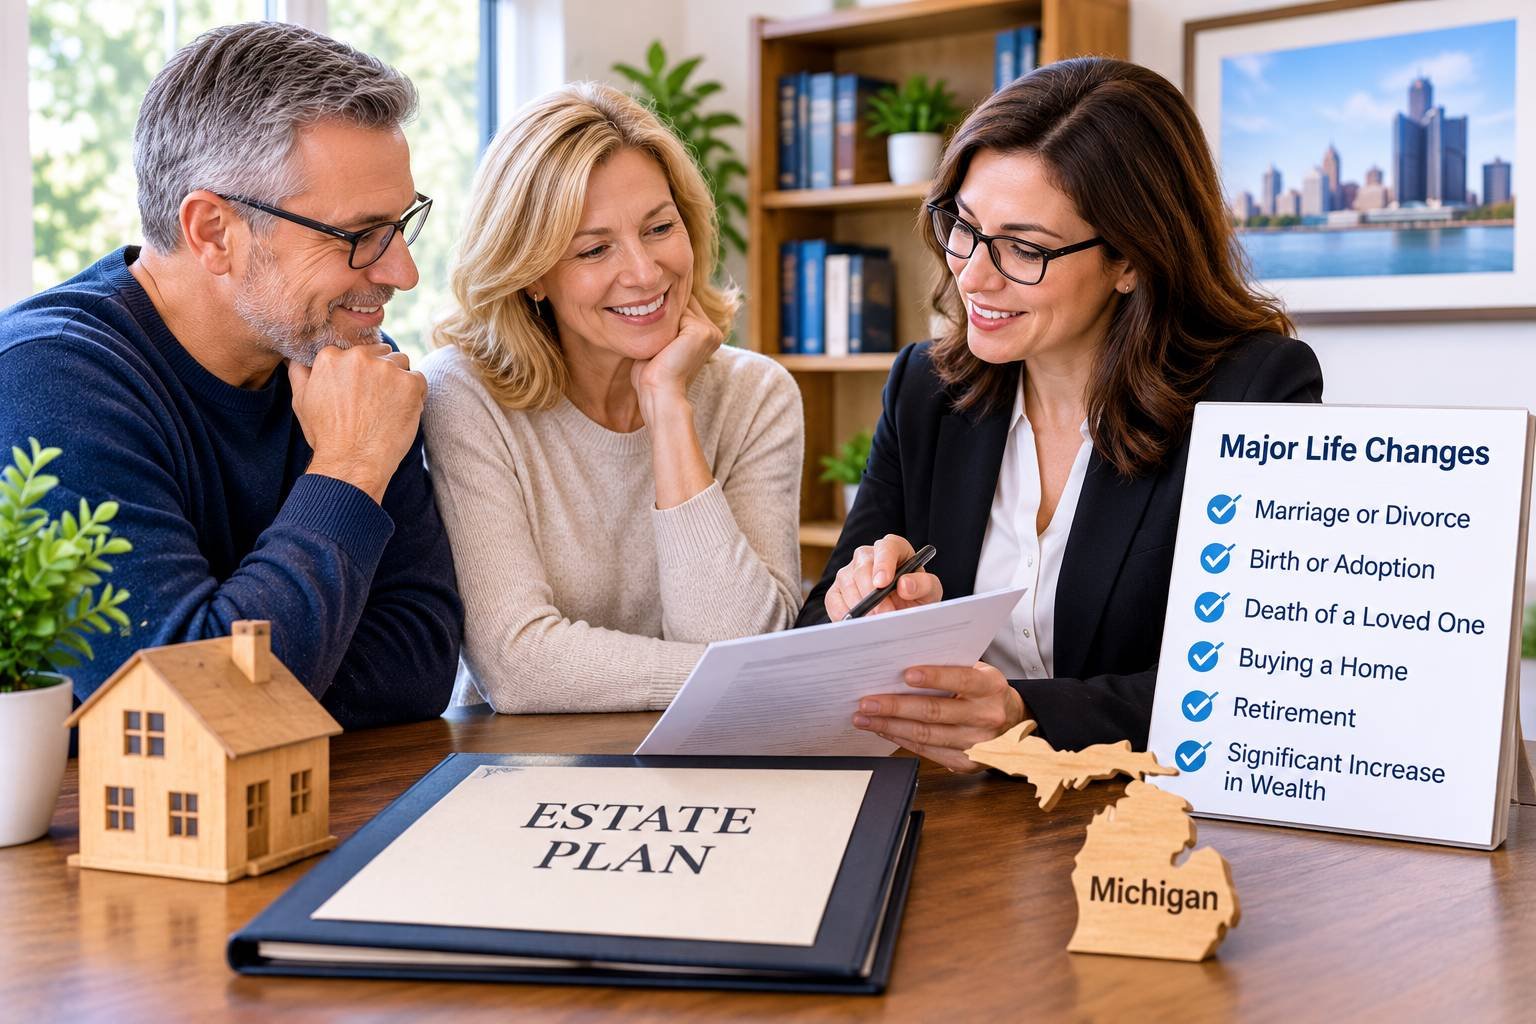
- An estate plan should be reviewed after major changes in family, health, finances, or residency.
- A will or trust is only one part of the plan. Beneficiary forms, account ownership, powers of attorney, and health care documents also matter.
- Michigan residents should ensure the people named to act on their behalf are still willing, able, and appropriate for the role.
- Annual check-ins can uncover outdated addresses, forgotten accounts, old beneficiaries, and changes in personal priorities.
An estate plan is meant to reflect real life and real-life changes. A marriage, divorce, new child, retirement, home purchase, health diagnosis, or move across the state can all affect whether existing documents still accomplish what you want. For Michigan families, an occasional review can be especially valuable when property, retirement accounts, family relationships, and caregiving needs have changed since the plan was signed.
Updating an estate plan does not always mean starting over. Sometimes the right step is a focused review of beneficiary designations or a new power of attorney. In other situations, such as a blended-family marriage or the sale of a closely held business, a broader conversation may be appropriate. Families considering their options can begin by reviewing guidance at https://www.mannorlawgroup.com/ann-arbor-estate-planning-lawyer/ to understand better the planning issues that may apply to their circumstances.
Why Major Life Changes Can Create Gaps
Estate planning works as a connected system. A will can name beneficiaries, nominate a guardian for minor children, and identify a personal representative. However, a will may not control every asset. Life insurance, retirement plans, payable-on-death bank accounts, jointly owned property, and assets titled in a trust may transfer according to separate documents or ownership arrangements.
For example, someone may update a Michigan will after remarriage but overlook a former spouse who is listed on an old retirement account beneficiary form. The account designation may still determine who receives that asset. Reviewing the full plan, rather than only one document, helps reduce conflicts between written wishes and account records.
Life Events That Should Trigger an Estate Plan Review
Marriage, Divorce, or Remarriage
Marriage can change priorities for property, decision-making authority, and long-term financial planning. Divorce may require prompt attention to beneficiary forms, powers of attorney, health care authorizations, and documents naming a former spouse in a fiduciary role. Remarriage can also bring new considerations involving children from prior relationships, a shared home, and the balance between a surviving spouse and adult children.
Birth, Adoption, or Changes in Caregiving
Parents of minor children may want to review guardian nominations and the individuals chosen to manage their children’s money. A family may also need to update its plan after becoming responsible for an aging parent, a grandchild, or an adult child with a disability. These circumstances can affect who should receive property, who should serve as trustee, and how funds should be held or distributed.
Death or Incapacity of a Named Decision-Maker
If a personal representative, trustee, financial agent, patient advocate, or guardian nominee dies, becomes ill, moves away, or is no longer a good fit, update the plan. Every important role should have a reliable backup. It is also wise to ask each person directly whether they remain willing to serve before keeping their name in the documents.
Health Changes and Long-Term Care Concerns
A serious diagnosis, hospitalization, memory concern, or increasing need for assistance can make incapacity planning more urgent. Michigan residents often use financial powers of attorney and health care documents to designate trusted individuals who can act on their behalf if they cannot. Michigan’s overview of advance directives and powers of attorney explains the value of making health care and financial decisions before an emergency occurs.
Moving, Buying Property, or Changing Assets
A move from Ann Arbor to northern Michigan, a new cottage near the Great Lakes, an inherited parcel of farmland, or a second home can change how property should be titled and managed. A substantial increase or decrease in wealth, the sale of a business, retirement, or a new investment account can also make older planning choices less suitable. If you move out of Michigan, documents should be reviewed under the laws of the new state.
What to Review When Updating an Estate Plan
Wills and Trusts
Read the documents with current circumstances in mind. Confirm that the people and charities named as beneficiaries still reflect your wishes. Check whether the personal representative or trustee remains the best person for the job. If a trust is part of the plan, review whether relevant assets are titled in the trust or otherwise coordinated with it.
Beneficiary Designations and Ownership Records
Make a list of every account or policy that has a named beneficiary. This commonly includes retirement accounts, life insurance, annuities, and payable-on-death or transfer-on-death accounts. Then review:
- Primary and contingent beneficiaries
- Spelling of names and current contact information
- Whether a beneficiary has died or is no longer appropriate
- Joint ownership arrangements for homes, vehicles, and bank accounts
- Whether the beneficiary plan aligns with the will or trust
Financial and Health Care Decision-Making Documents
Confirm that a trusted person is authorized to assist with financial matters if needed and that a patient advocate is named for health care decisions. Consider whether the documents identify alternates, provide sufficient practical authority, and align with your current preferences. Discuss your wishes with the people selected, particularly if there are strong views about treatment, living arrangements, or family communication.
Digital Assets and Personal Property
Update the inventory of online financial accounts, email addresses, cloud storage, social media profiles, digital photographs, domain names, and digital currency. Keep access details secure, rather than placing passwords directly in a will. Also consider creating clear instructions for sentimental items, such as family photographs, heirlooms, collections, or items connected to a Michigan family cottage.
A Practical Michigan Estate Plan Update Process
- Gather current copies of wills, trusts, deeds, insurance policies, beneficiary forms, and powers of attorney.
- Create or refresh a list of assets, debts, digital accounts, and professional contacts.
- Identify every life event that has occurred since the last review.
- Confirm that each named beneficiary, agent, trustee, and personal representative is still appropriate.
- Review account ownership and beneficiary designations separately from the will.
- Make legally valid updates rather than writing informal changes onto signed documents.
- Tell trusted family members where the original documents are stored and whom to contact in an emergency.
How Often Should Michigan Families Review Their Plans?
A light review once a year is a practical habit. It can be as simple as checking names, addresses, account beneficiaries, document storage, and changes in financial institutions. A more complete review should follow any major life event, especially marriage, divorce, death, birth, adoption, a major change in health, a move, or a significant change in assets.
Estate planning is not only about transferring property after death. It is also about providing useful instructions during illness, incapacity, and family transitions. Keeping documents current can give Michigan families clearer direction, reduce avoidable uncertainty, and help ensure that the plan still reflects the people and priorities that matter most.